JMC Woodmead celebrates first month of business
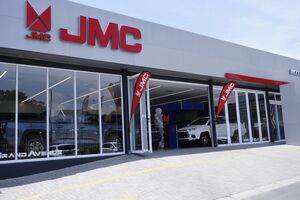
Bidvest McCarthy JMC Woodmead celebrated its first month of business in its new flagship showroom in Woodmead this week.
- Dealer News
- 18 November 2026
With the Financial Intelligence Centre Act (FICA) new Schedule 1 Amendments regarding motor vehicle dealers in place, a number of steps must be taken to ensure full FICA compliance.

In short, the changes include Motor Vehicle Dealers (MVDs) having to become Accountable Institutions instead of being just Reporting Institutions. These new measures are to ensure that vehicle dealers do not become a method of money laundering with ill-gotten gains.
There is more to FICA compliance than collecting and verifying documents. To be fully compliant, Accountable Institutions should comply with all obligations set out by the FIC.

DocFox, a leading FICA software provider, sheds some light on the key obligations:
1: Register with the FIC:
Accountable and Reporting Institutions are required to register with the Financial Intelligence Centre (FIC). Registration can take place on the FIC’s goAML EE online system, which can be accessed via the FIC’s website www.fic.gov.za
2. Appoint an anti-money-laundering /combating the financing of terrorism compliance officer:
The senior management or board of directors of an Accountable Institution needs to formally appoint a compliance officer to ensure compliance with FICAA (Financial Intelligence Centre Amendment Act). Ideally, the person appointed should have the competence and seniority to ensure the effectiveness of the accountable institution’s compliance function.
3. Develop an RMCP:
Accountable Institutions are required to apply a risk-based approach when establishing a business relationship and/or conducting a single transaction with a client. Part of this risk-based approach includes developing controls that mitigate and manage the business’s anti-money laundering risks and meet the FICAA requirements. All the controls developed and implemented should be documented to form part of their risk management and compliance programme (RMCP).
4. Perform customer due diligence:
Customer due diligence refers to the process of analysing information about an individual or legal person from multiple sources to ensure your clients are who they say they are.
It should also include verifying the identity of an individual or the registration of a legal person and this person’s address or location; obtaining information regarding the economic sector or occupation of your client; obtaining information about the nature of your client’s relationship with you; monitoring transactions; developing a risk-rating scheme to categorise your clients; checking data against third party data sources and identifying the source of funds.
It also includes identifying whether your client, a related party, authorised person or Ultimate Beneficial Owner (UBO) is on a sanctions list or has appeared in any adverse media.
5. Submit reports to the FIC:
Both Accountable and Reporting Institutions are obligated to report any suspicious behaviour or transactions to the FIC. This includes reporting any cash transactions in excess of the threshold of R49 999.
Other types of reports that can be submitted are known as suspicious transactions or suspicious activity reports (STRs/SARs). These reports should be submitted when there is either a transaction or activity by the client that appears to be suspicious or unusual.
Lastly, the fourth type of report that can be submitted is a terrorist property report (TPR). A TPR should be submitted when you think your client may possess or control property belonging to a client that could be linked to terrorism.
6. Record keeping:
FICAA requires accountable institutions to keep records of not only the due diligence that was carried out, but also details of any transactions that took place - including any counter-parties to those transactions. This is to ensure that evidence is available should the FIC or the authorities require it for an investigation or a prosecution.
Records must be kept for at least five years. It can be in paper or electronic form - as long as it is kept securely, safely, in confidence and is accessible by the FICAA compliance officer.
7. Ongoing Training:
According to section 43 of the FICAA, accountable institutions must provide ongoing training relating to AML/CFT with the purpose of complying with the provisions set out by FICAA and its internal RMCP.
Accountable institutions should bear in mind that the FICAA training requirement is not optional and businesses that fail to provide their employees with the required training, are regarded as non-compliant with the Act.

Bidvest McCarthy JMC Woodmead celebrated its first month of business in its new flagship showroom in Woodmead this week.
Combined Motor Holdings (CMH) has appointed Charles Webber as the new Group CEO.
Mazda Southern Africa has welcomed Group1 Mazda Southern Cape to its dealer network, strengthening the brand’s presence in the Southern Cape and creating a new home for Mazda customers in George and the surrounding region.
 Advertisement
 Advertisement
Cars are the ultimate symbol of freedom, independence and individualism. They offer the freedom to ‘go anywhere,’ whenever it suits and with whom one chooses.
Sarah Redshaw
Combined Motor Holdings (CMH) has appointed Charles Webber as the new Group CEO.
Cheap labour and state subsidies are the usual explanations for Chinese car prices. Research from think tanks and universities suggest the answer is far more complicated.
The first Volkswagen Tengo destined for an African customer rolled off the production line at Plant Kariega on 9 November 2026, making history in more ways than one.